IFRS 9 expected credit loss
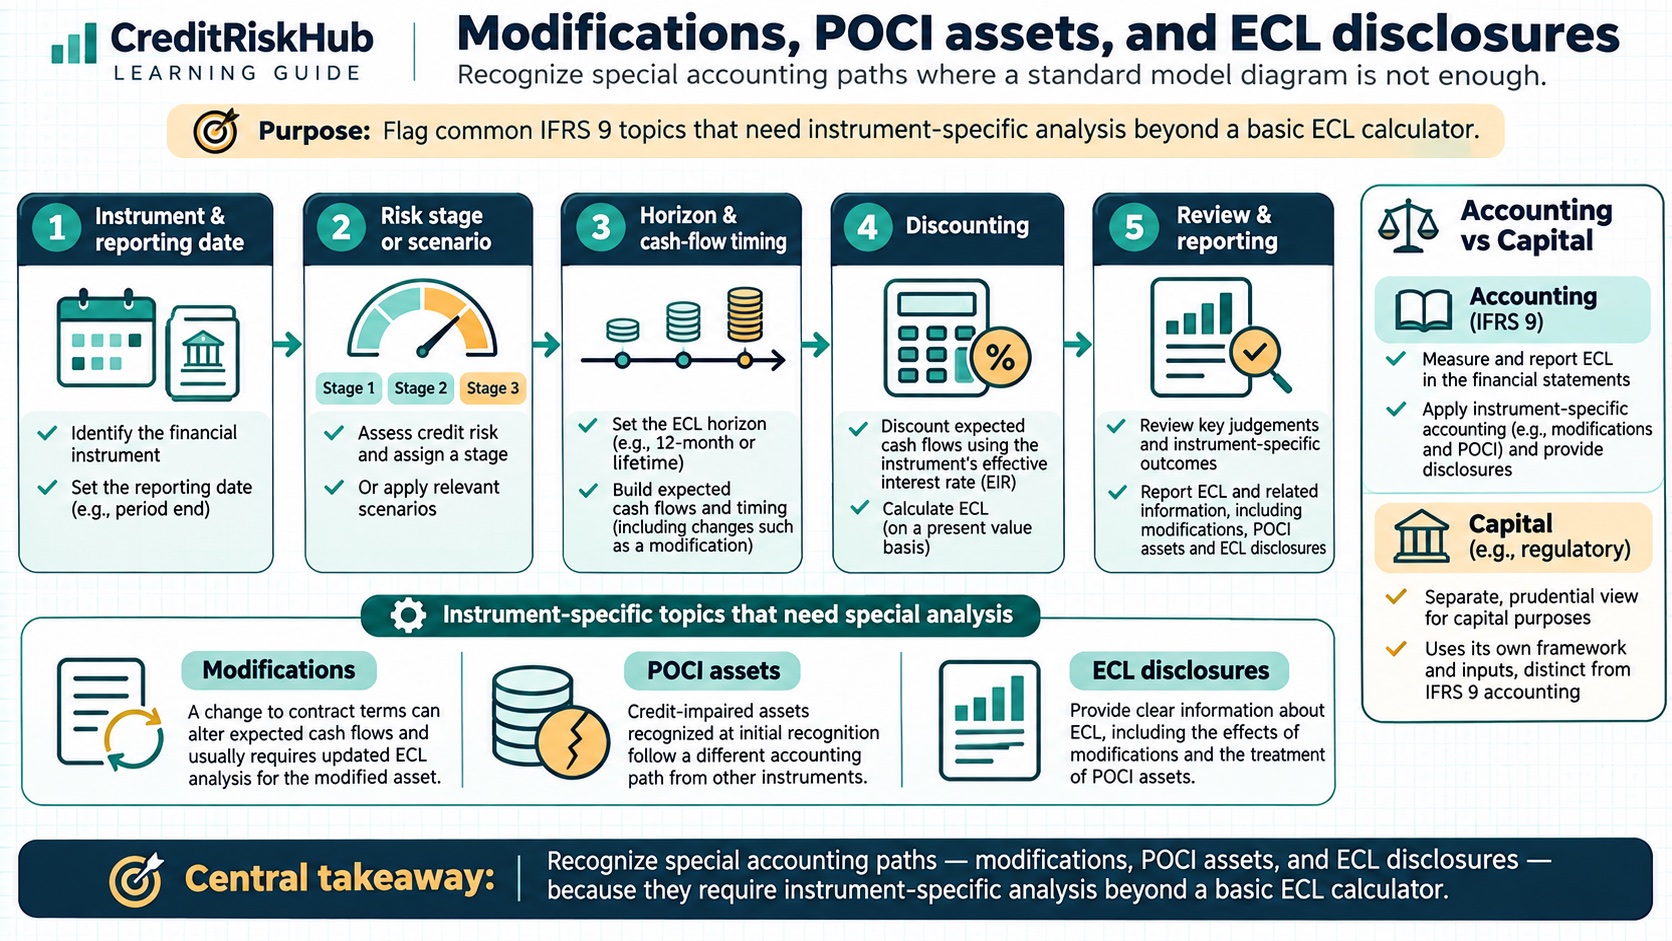
Modifications, POCI assets, and ECL disclosures
Recognize special accounting paths where a standard model diagram is not enough.
Purpose
Flag common IFRS 9 topics that need instrument-specific analysis beyond a basic ECL calculator.
Key terms
Hover over or focus a term for a quick definition, or open its glossary entry.
Key definitions
- Purchased or originated credit-impaired (POCI) assets are credit-impaired at initial recognition and have specific accounting treatment.
- A modification changes contractual cash flows and can affect derecognition, modification gain/loss, and impairment analysis.
No single formula covers all modification and POCI cases; apply the relevant IFRS 9 requirements to the instrument facts.Worked example
A loan modified after financial difficulty may require separate analysis of derecognition, revised cash flows, and whether it remains credit-impaired.
Detailed explanation
Not every exposure fits the standard three-stage teaching example. POCI assets use a credit-adjusted effective interest rate and recognize changes in lifetime expected credit losses under specific rules. Modifications, write-offs, derecognition, and assets already credit-impaired at initial recognition require separate accounting assessment.
A calculator can illustrate a defined cash-flow scenario but cannot decide the accounting classification of a contract. Maintain documentation for modification terms, original and revised cash flows, expected-life assumptions, write-off policy, overlays, and disclosure inputs. Consult the current licensed IFRS 9 text and the entity's accounting function for authoritative application.
Try a reproducible Python example
These examples use synthetic inputs and run locally in a browser worker. Edit the code, run it, and compare its output with the published example.
Runnable Python · local in your browser
Calculate year-by-year marginal and cumulative PD
Follow years 1–3 separately: conditional PD is the rate among survivors, marginal PD is the share of the original cohort defaulting in that year, and cumulative PD adds those marginal shares.
Output
Run the code to see the output.
Runtime loads only after you press Run. Code runs in a separate browser worker with a 10-second limit and a 20,000-character output cap. Use synthetic examples only; browser execution is not a secure environment for secrets or sensitive records.
Runnable Python · local in your browser
Calculate survival-weighted, discounted ECL
Combine period marginal PD, LGD, EAD, discount factors, and two scenario weights in a small illustrative horizon.
Output
Run the code to see the output.
Runtime loads only after you press Run. Code runs in a separate browser worker with a 10-second limit and a 20,000-character output cap. Use synthetic examples only; browser execution is not a secure environment for secrets or sensitive records.
Assumptions
- The contract, initial-recognition status, modification terms, and entity accounting policy are reviewed by qualified accounting personnel.
Limitations
- General summaries cannot decide instrument classification or derecognition.
- Disclosure requirements depend on the standard, materiality, and reporting circumstances.
References
- IFRS 9 Financial Instruments — IFRS Foundation
- Guidance on credit risk and accounting for expected credit losses — Basel Committee on Banking Supervision
Educational material only. Methods and examples are simplified; state and validate the assumptions required for your use case.