Loss given default (LGD)
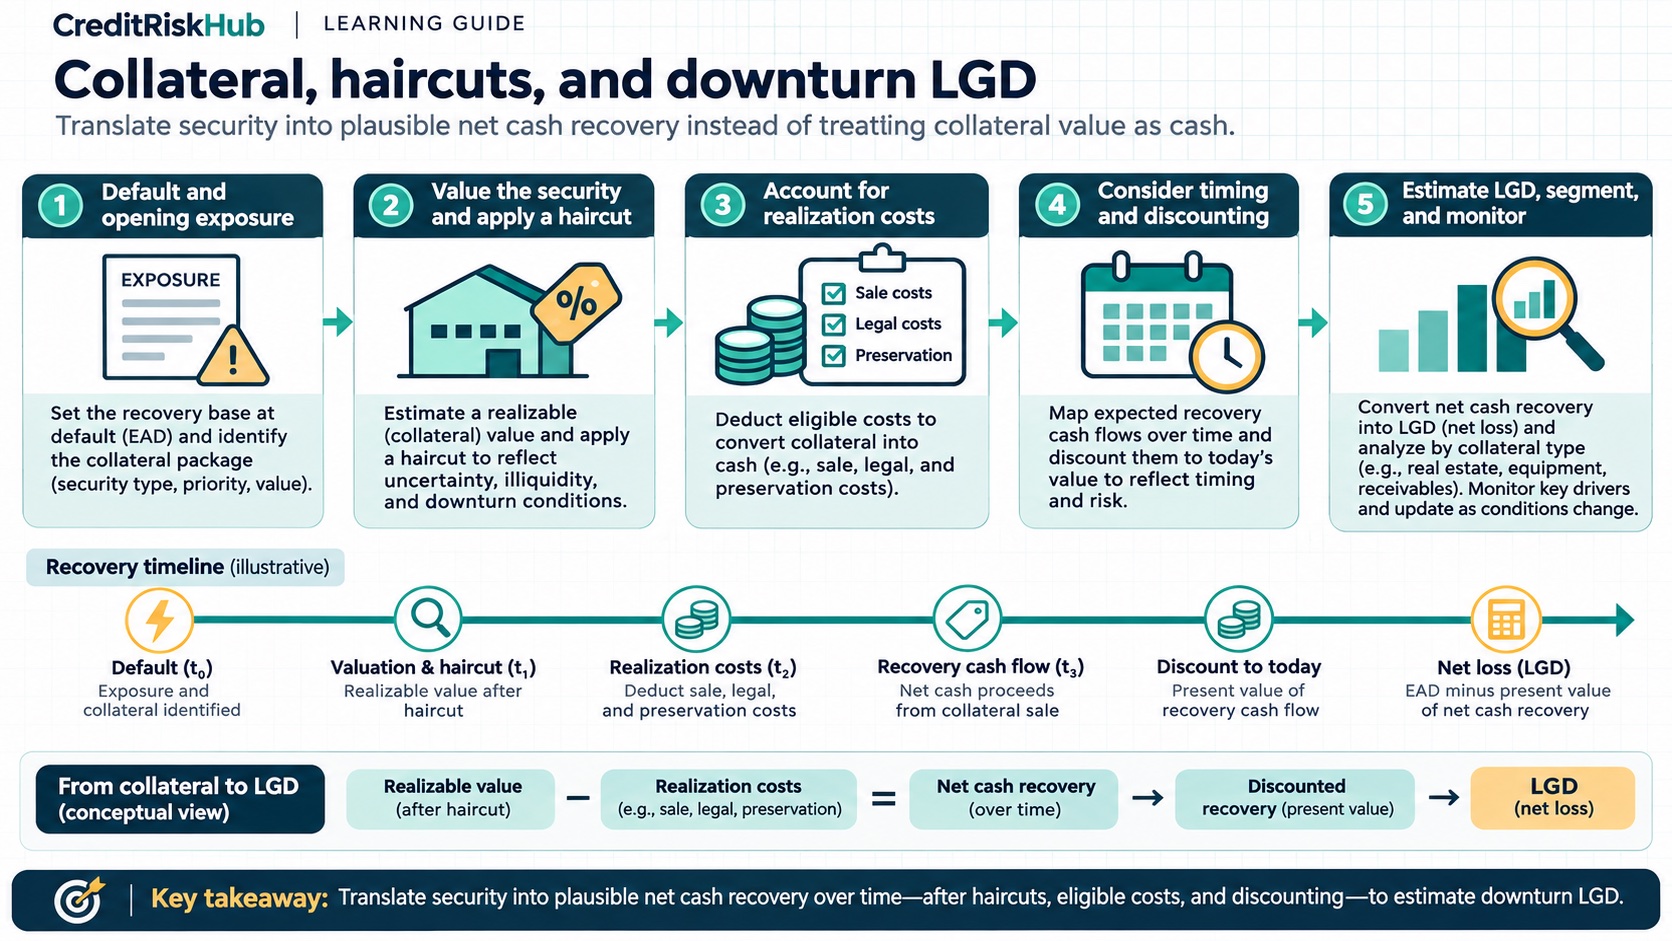
Collateral, haircuts, and downturn LGD
Translate security into plausible net cash recovery instead of treating collateral value as cash.
Purpose
Explain valuation, haircut, realization cost, and timing considerations in a collateralized LGD estimate.
Key terms
Hover over or focus a term for a quick definition, or open its glossary entry.
Key definitions
- Collateral is an asset or guarantee supporting repayment after borrower default.
- A haircut reduces a stated collateral value to reflect realization uncertainty, market movement, or cost.
Illustrative net collateral recovery = appraised value × (1 − haircut) − realization costs.Worked example
A $200,000 appraisal with a 25% haircut and $10,000 of costs yields $140,000 before discounting and allocation.
Detailed explanation
Collateral reduces loss only to the extent it can be enforced and converted into timely net proceeds. Review lien priority, legal enforceability, valuation date, marketability, selling costs, maintenance, and recovery delay. Allocate proceeds consistently when multiple facilities or creditors share the same security.
A haircut is a transparent adjustment, not a substitute for recovery evidence. Downturn LGD and collateral rules can be prescribed or constrained under prudential frameworks; these should not be presented as the same thing as an IFRS 9 forward-looking recovery estimate. Show the gross value, each adjustment, expected timing, and resulting present value so users can see where the modeled benefit comes from.
Try a reproducible Python example
These examples use synthetic inputs and run locally in a browser worker. Edit the code, run it, and compare its output with the published example.
Runnable Python · local in your browser
Link re-default episodes and calculate discounted LGD
Apply a declared synthetic 12-month cure probation and compute two episode LGDs from bounded cashflow lists.
Output
Run the code to see the output.
Runtime loads only after you press Run. Code runs in a separate browser worker with a 10-second limit and a 20,000-character output cap. Use synthetic examples only; browser execution is not a secure environment for secrets or sensitive records.
Runnable Python · local in your browser
Discount recovery cash flows for workout LGD
Discount synthetic recoveries and costs to default date and calculate a capped loss fraction.
Output
Run the code to see the output.
Runtime loads only after you press Run. Code runs in a separate browser worker with a 10-second limit and a 20,000-character output cap. Use synthetic examples only; browser execution is not a secure environment for secrets or sensitive records.
Assumptions
- Collateral is enforceable, attributable to the exposure, and valued at a date relevant to the model purpose.
Limitations
- Appraisal values may be stale, non-liquid, or legally unavailable at default.
- Downturn conditions and prudential floors are jurisdiction- and method-specific.
References
- Basel Framework: IRB approach and credit-risk components — Basel Committee on Banking Supervision
- Guidelines on PD estimation, LGD estimation and treatment of defaulted assets — European Banking Authority
Educational material only. Methods and examples are simplified; state and validate the assumptions required for your use case.